What if the warning signs of business failure could be detected years before a company runs out of cash?
Anticipating financial distress is a major challenge for Credit Managers and finance professionals. Beyond traditional credit scores and financial statements, understanding changes in customer behaviour and identifying early warning signals can make the difference between reacting to a crisis and preventing one.
In this new Words of Experts interview, Professor Nick Wilson FCICM joins Luke Sculthorp FCICM, Commercial Director UK & Ireland at My DSO Manager, to explore business failure prediction, artificial intelligence, human judgement and the opportunities emerging from e-invoicing.
Leeds University Business School
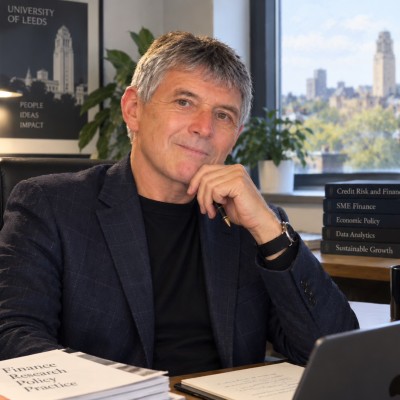
Professor Nick Wilson is Professor of Credit Management and Finance at Leeds University Business School and Director of the Credit Management Research Centre.
With approximately 30 years of research into credit risk, financial distress and corporate failure, he has been exploring predictive analytics since the mid-1990s, when he began using neural networks to model credit risk and anticipate company failure.
His work bridges academic research and practical financial decision-making, offering a distinctive perspective on how businesses can identify emerging risks earlier and strengthen their financial resilience.
From reactive Credit Management to proactive risk anticipation
Traditional credit assessment relies heavily on historical information: annual accounts, payment history and external credit scores. Although these indicators remain important, they do not always reveal how a customer's financial situation is changing.
For Professor Nick Wilson, the distinction between reactive and proactive Credit Management lies in the ability to understand the direction of risk rather than simply assess a company's past performance.
"A reactive credit function looks at what a customer was: last year's accounts, payment history, the bureau score. A function that's genuinely ahead of risk looks at what the customer's becoming."
This forward-looking approach requires Credit Managers to monitor changes in payment behaviour, working capital pressures, sector conditions, competitive positioning and the wider economic environment.
A customer may appear financially stable according to its latest published accounts while already showing signs of deterioration through its trading behaviour.
The objective is therefore to move from a static assessment of creditworthiness to continuous monitoring of financial risk.
"Being ahead of risk means acting on trajectory, not the snapshot."
Business failure: Early warning signs can appear years in advance
One of the most important findings from Nick Wilson's research concerns the timing of financial distress.
Having studied UK company failures for approximately three decades, using extensive company and director records, he explains that many indicators of financial difficulty remain remarkably consistent over time.
"Distress usually shows up two or three years before failure."
According to his research, financial distress often becomes visible in working capital and balance sheet indicators before it appears in headline profitability figures.
Among the key indicators to monitor are:
- Changes in debtor days and payment behaviour, which may indicate increasing pressure on customer liquidity.
- Working capital deterioration, revealing growing financing needs or operational imbalances.
- Increasing dependence on trade credit, when suppliers become a more significant source of financing.
- Greater reliance on bank financing, potentially indicating pressure on available liquidity.
- Changes in the cash conversion cycle, showing how efficiently a business converts its activities into cash.
These indicators are particularly important because a profitable company is not necessarily a financially resilient company.
"Quite often we see profitable, innovative firms failing. They don't run out of orders. What they do run out of is cash at the wrong moment."
For Credit Managers, this highlights the importance of looking beyond revenue and profitability to understand cash flow dynamics, payment discipline and the sustainability of customer financing.
Beyond financial statements: Identifying behavioural warning signals
Financial accounts provide valuable information, but they represent only one part of an effective credit risk monitoring system.
Nick Wilson also highlights the importance of behavioural, administrative and operational indicators that may reveal financial difficulties before they become visible in published results.
These include late filing of accounts, audit qualifications, county court actions, changes in company directors and sudden variations in trading patterns.
Individually, these events do not necessarily predict insolvency. However, when analysed alongside financial information and payment behaviour, they can contribute to a more complete assessment of customer risk.
Nick also draws attention to a source of information that organisations frequently underestimate: the knowledge and experience of their own Credit Managers.
"The earliest warning system usually sits inside the business, and that's the credit manager's knowledge of the customer base and the market."
Through their daily interactions with customers, Credit Managers develop an understanding of commercial relationships, payment habits, sector conditions and changes in behaviour.
This operational knowledge can reveal warning signals that are difficult to capture through standardised financial models alone.
Combining external financial data with internal customer knowledge is therefore essential to developing a more reliable and actionable view of credit risk.
Artificial intelligence in Credit Management: From data analysis to better decisions
Artificial intelligence is opening new possibilities for credit risk assessment, predictive analytics and the early detection of financial distress.
However, for Professor Nick Wilson, the underlying analytical principles are not entirely new.
In the mid-1990s, he was already working with neural networks to model credit risk and predict company failure, long before AI became a mainstream business topic.
At that time, the principal limitations were computing power and access to data. Today, sophisticated analytical tools are widely available, but organisations still face challenges concerning data quality, consistency, relevance and timeliness.
AI can help credit teams process large volumes of information, identify patterns and detect changes in customer behaviour. Its practical value may include better risk selection, earlier intervention and stronger fraud controls.
Yet technology adoption does not automatically translate into improved financial performance.
A company may implement advanced analytical solutions without fundamentally changing how credit decisions are made.
"AI's job is to multiply credit expertise, not replace it."
For AI to deliver meaningful value, it must be integrated into business strategy, operational processes and the daily work of the professionals closest to customer information.
The real challenge is not simply to automate credit analysis, but to transform analytical insights into timely, informed and effective decisions.
Why human judgement remains essential in credit risk management
As artificial intelligence becomes more sophisticated, the role of the Credit Manager is evolving.
Rather than simply receiving automated scores or recommendations, credit professionals should actively contribute to the design and operation of analytical systems.
"The credit professional should be the architect of the system, not somebody waiting for the system to give it an answer."
This perspective places human expertise, commercial understanding and professional accountability at the centre of digital transformation.
Algorithms can identify statistical relationships and generate risk assessments, but experienced professionals remain essential for interpreting unusual circumstances, understanding customer relationships and deciding how to respond.
Nick also highlights an organisational challenge: technology initiatives are sometimes developed without sufficient involvement from operational teams.
When the experience of Credit Managers is excluded from system design, businesses risk creating disconnected technological experiments rather than integrated decision-support systems.
Successful AI adoption therefore requires collaboration between management, technology specialists and credit professionals.
"A model can do all the scoring, but a person has got to own the decision."
Artificial intelligence can strengthen credit decisions, but it does not eliminate the need for human judgement or accountability.
E-invoicing: A new source of intelligence for credit risk assessment?
The development of electronic invoicing and structured financial data represents another important transformation for Credit Management.
With the UK moving towards mandatory e-invoicing for VAT invoices from 2029, and the European Union advancing digital reporting reforms through its VAT in the Digital Age initiative, the way businesses generate and exchange financial information is evolving.
Although e-invoicing is often approached as a regulatory or administrative requirement, Nick Wilson sees a broader opportunity for credit risk management.
"It's much more than compliance. It's potentially a very big change in the UK credit information infrastructure."
Traditional credit assessment frequently depends on financial statements describing a company's position at a historical point in time.
Structured electronic invoicing could progressively enable a more timely view of commercial transactions, including trade flows, payment discipline, cash flow pressures and changes in customer behaviour.
This evolution could help credit teams identify emerging difficulties earlier and strengthen fraud prevention through more structured and verifiable invoice information.
However, Nick emphasises that technology alone will not eliminate risk. Data access, permissions, governance and model design will remain essential to ensuring that information is used appropriately.
Could early adoption of e-invoicing become a positive credit signal?
One particularly interesting perspective raised during the interview concerns the potential relationship between digital maturity and creditworthiness.
Nick suggests that companies adopting accredited electronic invoicing systems ahead of regulatory deadlines may send a positive signal to their trading partners.
Early adoption could indicate that a business has organised systems, more transparent transaction records and the capacity to exchange verifiable financial information.
In this context, e-invoicing could evolve from an administrative obligation into an additional source of intelligence for credit assessment.
Rather than relying exclusively on retrospective financial information, Credit Managers may increasingly be able to use more current indicators of commercial activity and payment behaviour, subject to appropriate data-sharing arrangements.
These developments could contribute to a more dynamic approach to risk monitoring, while maintaining the need for sound governance and professional interpretation.
The future of Credit Management: Combining AI, data and professional expertise
Throughout the interview, Professor Nick Wilson returns to one central principle: technology should strengthen the ability of credit professionals to make better decisions.
When asked which emerging risk businesses may still be underestimating, he identifies AI-enabled fraud.
At the same time, he remains optimistic about the profession's future, highlighting Credit Management's history of adopting new technologies and the opportunities associated with agentic AI.
For Credit Managers, this evolution creates new responsibilities and opportunities.
Financial analysis remains fundamental, but the profession increasingly requires the ability to interpret behavioural data, understand commercial conditions, work with advanced analytical tools and translate early warnings into practical action.
The competitive advantage will not necessarily belong to organisations with the most data, but to those capable of identifying meaningful changes early and responding before financial difficulties escalate.
Conclusion: From predicting financial distress to protecting business resilience
Professor Nick Wilson's research offers a clear perspective on the future of Credit Management.
Business failure is rarely an entirely unexpected event. In many cases, the warning signs begin appearing well before a company experiences a critical liquidity problem.
Working capital movements, payment behaviour, administrative indicators and customer knowledge can all contribute to earlier detection.
Artificial intelligence and structured financial data create opportunities to identify these patterns more effectively, but they do not remove the need for experienced professional judgement.
The Credit Manager's role is therefore becoming increasingly strategic: anticipating risk, interpreting information and helping businesses make informed decisions before problems become critical.
Ultimately, the future of Credit Management is not simply about predicting which companies may fail. It is about recognising the signals early enough to protect cash flow, manage exposure and support more resilient commercial relationships.
Watch the full interview with Professor Nick Wilson
Discover the conversation between Professor Nick Wilson FCICM and Luke Sculthorp FCICM in 7 Minute Empowerment, the podcast by My DSO Manager.
Explore the early warning signs of business failure, the role of AI in credit risk management, human judgement and the impact of e-invoicing on the future of the profession.
Thank you for following this Words of Experts interview with Professor Nick Wilson. Discover more expert perspectives on Credit Management, customer risk and the future of Order-to-Cash.
 Stay connected for more expert interviews and insights into Credit Management best practices.