What is credit management? Credit management is the coordinated management of customer credit risk, payment terms, invoicing, disputes and receivables to support sales while protecting cash flow.
Credit management is the discipline of managing the credit a company grants to its customers. Its purpose is deceptively simple: to get paid for the work delivered, on time and without compromising the customer relationship. Achieving this objective involves far more than chasing overdue invoices. It requires coordinated decisions throughout the commercial process, from prospecting to final payment.
Every sale on payment terms is also a financing decision. The supplier delivers goods or services today and receives the cash later. That financing has a cost, exposes the supplier to risk and ties up working capital. Managing it is a core business responsibility, not a secondary administrative task.
Credit management, credit risk management and debt collection: what is the difference?
These activities are related but they are not interchangeable. Credit management covers the entire customer credit lifecycle; risk management and collection are two of its essential components.
Credit management
Coordinates credit decisions, commercial terms, invoicing, disputes, receivables and cash performance throughout the customer relationship.
Credit risk management
Assesses the probability and consequences of non-payment and determines appropriate limits, guarantees and exposure monitoring.
Debt collection / cash collection
Secures the payment of receivables, through preventive action, dispute resolution, amicable follow-up and, when necessary, legal recovery.
A business may have effective debt collection but weak credit management if it repeatedly creates billing errors, grants inappropriate terms or accepts excessive customer risk.
What is credit management?
Credit management brings together customer risk assessment, credit decisions, contractual protection, invoicing quality, dispute resolution, cash collection and performance management. The ultimate goal is to support profitable sales while securing their conversion into cash.
Secure sales
Evaluate customers, set appropriate credit limits and agree on sustainable payment conditions.
Convert revenue into cash
Prevent avoidable delays, resolve disputes and obtain payment when due.
Improve the business
Use payment difficulties to identify weaknesses in sales, contracts, delivery, billing and communication.
Late payment is not always caused by a customer who refuses to pay. It may reflect an incorrect purchase order, an invoice sent to the wrong entity, an unresolved delivery issue, missing documents or an inefficient approval process. The accounts receivable ledger is often where problems created elsewhere in the company become visible.
Why is credit management still underestimated?
Many businesses focus primarily on turnover and margins. Payment conditions are sometimes discussed only at the end of a commercial negotiation, although they influence the economics and risk of the sale from the outset. Smaller companies may be especially exposed when no one has a clear mandate to manage customer credit and overdue receivables.
Yet the absence of a dedicated credit management department does not remove the need for credit management. In a smaller company, its principles can be implemented through clear rules shared by sales, finance, customer service and management.
A sale is not fully successful merely because an invoice has been issued. The commercial transaction is completed when the agreed amount is paid and the customer relationship remains sound.
Why do suppliers grant payment terms?
Trade credit has deep historical roots. As commerce expanded, the time required to transport goods, exchange documents and settle payments created a natural gap between delivery and cash receipt. Instruments such as bills of exchange and documentary credits emerged in this context.
Today, granting payment terms is often commercially necessary. But it is not neutral: the supplier effectively finances its customer, generally without a separately priced loan and without certainty of repayment. The longer the terms and the larger the exposure, the more cash and risk the supplier carries. See also our guide to customer credit assessment.
Commercial opportunity
Appropriate credit terms can help win business and build long-term relationships with financially sound customers.
Financial commitment
The same terms consume working capital and create exposure to delays, disputes and potential bad debts.
What does a credit manager do?
The credit manager works across the entire quote-to-cash process, in cooperation with sales, finance, accounting, legal, operations and customer service. The job combines commercial judgment, financial analysis, negotiation, process improvement and the ability to coordinate decisions.
1. Before prospecting
- Define customer segments and associated risk profiles.
- Set standard payment terms and approved payment methods.
- Contribute to terms and conditions of sale, including late-payment provisions and retention of title where relevant.
- Establish a credit management policy and approval responsibilities.
2. Prospecting and negotiation
- Assess customer creditworthiness.
- Set and review credit limits based on risk and expected business.
- Negotiate terms, deposits and payment methods.
- Support sales teams in developing business with reliable customers.
3. Contracting
- Check the balance of reciprocal commitments.
- Agree on invoicing milestones, down payments and acceptance criteria.
- Review contractual protections: retention of title, suspension or termination rights, acceleration clauses and late-payment provisions, subject to applicable law.
4. Invoicing and dispute resolution
- Ensure invoices are accurate, timely and consistent with contracts.
- Check required invoice details and customer references.
- Resolve disputes promptly and address their root causes.
- Improve cooperation between sales, operations and accounting.
5. Cash collection
- Organise preventive communication and timely follow-up, with a collection organisation adapted to the company.
- Prioritise accounts according to risk, value and the reasons for non-payment.
- Negotiate payment commitments and resolve obstacles.
- Escalate appropriately to legal collection, insurers or specialist providers when necessary.
6. Performance and working capital
- Monitor DSO, overdue receivables, losses and collection efficiency.
- Forecast cash receipts and assess credit exposure.
- Improve processes across the business.
- Provide management with reliable indicators and actionable recommendations.
The credit manager's role also extends to receivables accounting, payment allocation, doubtful-debt provisions and information systems. These are interconnected responsibilities, even when operational ownership is shared with other departments.
Digital credit management: expertise enhanced by technology
Credit managers operate at the intersection of commercial and financial information, both inside the business and with its customers. Their effectiveness depends on whether the right people can access reliable information at the right time: credit assessments, invoices, account statements, payment commitments, disputes and supporting documents.
Modern credit management software can connect ERP, CRM, accounting and customer communication systems, coordinate workflows and give a consolidated view of receivables. Automation can handle repetitive work and help teams concentrate on negotiations, decisions and complex disputes.
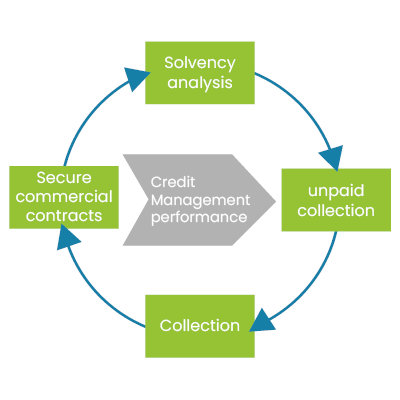
Four dimensions of performance
Understand risks, commercial realities and the causes of non-payment.
Provide workflows that match actual operational needs rather than forcing teams into rigid processes.
Connect business systems and make information available without manual re-entry.
Support analysis, prioritisation and communication when the underlying data and processes are reliable. Explore AI in cash collection.
AI cannot compensate for poor customer data, broken workflows or a lack of professional judgment. Its value depends on the quality of the foundations on which it operates. The objective is not to multiply automated reminders; it is to remove the causes of late payment and make each intervention more relevant.
My DSO Manager illustrates this approach by bringing credit risk, cash collection, dispute management, reporting and connected workflows together in a single credit management environment.
How to measure credit management performance
Example: the cash impact of reducing DSO by five days
Consider a company generating EUR 36.5 million in annual credit sales, with sales spread evenly over the year. Its average daily sales are approximately EUR 100,000. If it sustainably reduces its DSO from 60 to 55 days, it can release approximately EUR 500,000 in cash from receivables, all else being equal.
EUR 36.5m
5 days
EUR 500,000
Illustrative calculation: EUR 36,500,000 / 365 x 5 = EUR 500,000. This is a working-capital release, not additional revenue or profit. Actual results depend on seasonality, sales mix, VAT treatment and the DSO calculation method.
To achieve such a reduction, it may be more effective to correct recurring invoice errors and resolve disputes quickly than to increase the number of automated reminders. The cash collection process improvement guide examines this relationship in more detail.
Because credit management spans the entire sales process, it cannot be assessed with a single indicator. A low DSO may reflect short contractual terms rather than superior collection performance; a high collection activity volume may simply indicate that many preventable problems remain unresolved.
| Indicator | What it measures | What to watch |
|---|---|---|
| DSO (Days Sales Outstanding) | Average time sales remain in receivables. | Separate the effect of contractual payment terms from payment delays. |
| Overdue ratio | Share of receivables past due. | Analyse ageing, customer segments and dispute causes. |
| Bad debt ratio | Losses or doubtful receivables relative to sales, according to the defined methodology. | Use consistent definitions across periods. |
| Collection effectiveness | Progress in converting due receivables into cash. | Distinguish recovered cash from promises or actions completed. |
| Credit risk coverage | Exposure relative to credit limits, guarantees and insurance. | Monitor uncovered and concentrated risk. |
| Dispute resolution time | How quickly commercial and administrative obstacles are resolved. | Track recurrence, not only closure speed. |
| Receivables-related working capital | Cash tied up in customer balances. | Connect improvements to liquidity and financing needs. |
Example: why a payment delay is not always a collection problem
Suppose a customer has not paid a significant invoice because the purchase order reference is missing. Repeated reminders will not fix the issue. The useful action is to identify the discrepancy, correct the document and prevent the same error on future invoices. The credit manager's contribution is therefore both immediate (obtaining payment) and structural (improving the invoicing process).
From overdue invoices to process improvement: a practical case
A customer regularly pays 20 days late. Collection reports initially suggest a debtor behaviour problem. However, the credit manager discovers that invoices are issued before the customer's service-acceptance workflow is complete. Each invoice is held for manual validation, and the collection team only sees the delay after the due date.
Instead of increasing reminder frequency, the credit manager works with sales, operations and billing to align acceptance milestones, required references and invoice issuance. The result can be fewer disputes, more predictable payment dates and less collection effort. This is an illustrative scenario, not a claim about a specific customer or a quantified real-world result.
Conclusion: credit management is a collective performance discipline
Credit management secures profitable growth, protects cash flow and improves the quality of commercial relationships. Its effectiveness depends on actions taken before, during and after the sale. It is also a powerful way to identify internal dysfunctions and correct them.
Ultimately, getting paid on time is not just the credit manager's responsibility: it is the result of a well-managed business process. The credit manager provides the expertise, coordination and visibility that make this collective performance possible.
Explore the credit management process in more detail
These practical guides examine the main stages of the customer credit cycle, from assessing risk to resolving unpaid receivables.
Assess your customers
Evaluate customer credit risk before granting payment terms.
Improve business processes through cash collection
Turn overdue-payment causes into improvements across the business.
Artificial intelligence in cash collection
Understand what AI can improve and where professional expertise remains essential.
Bad debts collection
Explore the options when amicable collection is no longer sufficient.
This English guide is adapted from the original articles on CreditManagement-Tools.com and Etrepaye.fr. The original performance illustration is retained.