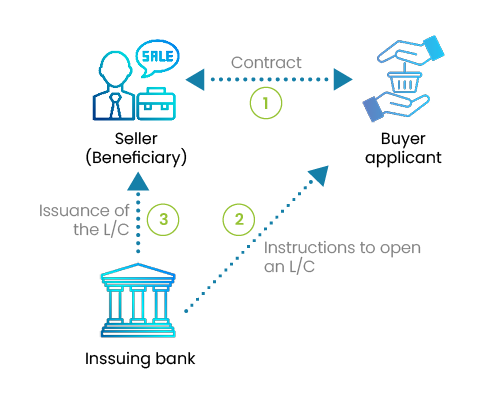
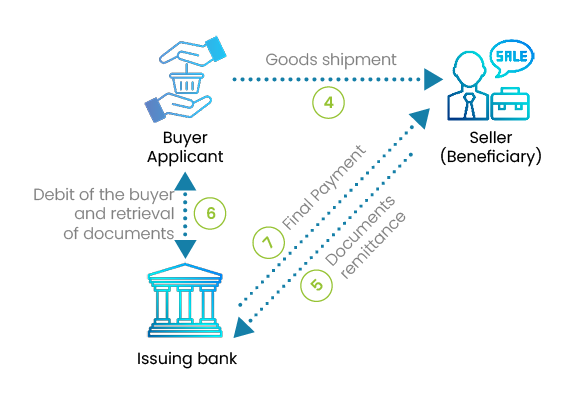
A letter of credit can help secure international trade, but the protection it provides depends on the type of undertaking issued by the bank. For a Credit Manager, the essential question is whether the bank is expected to pay for the transaction or step in if the buyer fails to pay. Terminology matters: In international banking, a commercial letter of credit is generally another name for a documentary credit. A standby letter of credit (SBLC), however, is generally used as a bank-backed security instrument. The expression letter of credit on its own is therefore ambiguous. When negotiating an export sale, the seller may want a bank to assume a payment obligation. Two commonly used structures answer different needs: Both may create independent bank undertakings. Neither should be assessed solely by its name: the wording, governing rules, expiry, available amount and required documents determine how it works. Under a commercial letter of credit, the importer requests issuance of a credit in favour of the exporter. The issuing bank commits to honour a presentation that complies with the credit's terms and applicable rules, usually the UCP 600 of the International Chamber of Commerce. An advising bank may authenticate and advise the credit to the exporter. A confirming bank may add its own independent undertaking. An advising bank is not automatically a confirming bank, and its involvement does not, by itself, transfer the issuing bank's credit risk. Once the goods are shipped or the service is performed, the exporter presents the stipulated documents to the designated bank. The bank examines the documents, rather than independently verifying the physical goods or contractual performance. A discrepancy may prevent payment unless appropriately resolved. For a full explanation of the process, see The Documentary Credit. A standby letter of credit (SBLC) generally serves as security rather than the normal payment method. The seller invoices the buyer under the commercial contract. If the buyer fails to pay and the conditions specified in the standby are met, the seller may present a demand to the issuing bank. Standbys are commonly issued subject to ISP98 (ICC Publication 590), although some are subject to UCP 600. A demand guarantee subject to URDG 758 is a related but distinct instrument. The governing rules and wording must be checked rather than assumed. Important: a standby is not an unconditional promise to reimburse any unpaid invoice. Payment may depend on the exact wording of the demand, supporting declarations, deadlines, place of presentation and other documentary conditions. A standby is also not identical to a French-law suretyship (cautionnement). Read the dedicated tutorial: The Standby Letter of Credit. Neither instrument is inherently better. A commercial credit may be appropriate for a one-off shipment with documentary control; a standby may better suit recurring deliveries on open-account terms, where normal payment remains the buyer's responsibility. Credit management principle: the purpose is not to accumulate banking instruments, but to select a protection that matches the actual commercial exposure and can be enforced when needed.Letter of Credit: Payment Instrument or Bank Guarantee?
Two different functions: payment and security
Commercial letter of credit: the bank pays against documents
Standby letter of credit: a bank guarantee in economic substance
Commercial letter of credit vs standby letter of credit
Criterion
Commercial letter of credit
Standby letter of credit
Primary purpose
Payment for a transaction
Security against a specified default
Normal settlement
Bank honours complying documents
Buyer pays directly
Bank is called upon
In the ordinary course of settlement
Usually following a specified failure
Typical documents
Commercial and transport documents stipulated by the credit
Demand and default statement or other documents stipulated by the standby
Common rules
UCP 600
ISP98; sometimes UCP 600
Key risk for seller
Documentary discrepancies and bank/country risk
Non-compliant demand, expiry and bank/country risk
What should the Credit Manager check?
Category's rubrics
Learn about its export customersThe documentary creditThe letter of creditThe letter of credit standbyCash against documentsProjects managementSingle risk insurances
Comments
Comment this page
Comments are subject of editor's review before publication
Articles on the same topic
Category
Credit Management
03-04-2026
Credit Management, meaning the management of credit granted to its customers, is a discipline increasingly identified as strategic by companies. Indeed, the challenges of credit management are...
Category
My DSO Manager presentation, collection and credit management software
04-22-2025
My DSO Manager is a market-leading credit management and cash collection software software. Its innovative SaaS (Software as a Service) solution allows to digitize the Order to Cash process,...
Rubric
Balance Sheet Ratios: Formulas, Examples & Credit Risk
11-05-2026
Key Balance Sheet Ratios: How to Calculate and Interpret Them Balance sheet ratios help credit managers assess a customer's financial resilience, short-term liquidity and ability to meet payment...