A balance sheet reveals how a company finances its assets, how much it relies on creditors, and whether its financial structure can support its operating cycle. Understanding it is essential when assessing a customer's creditworthiness. A balance sheet provides a snapshot of a company's financial position at a particular date. It presents its assets and the sources used to finance them: equity and liabilities. By definition, total assets equal total equity plus liabilities. Assets include non-current assets, such as property and equipment, and current assets, such as inventory, trade receivables and cash. Financing comes from shareholders' equity, borrowings, trade payables and other liabilities. A strong equity base generally improves financial resilience, because the company is less dependent on external creditors. However, the level of debt must be assessed in relation to cash generation, maturity dates, the value and liquidity of assets, and the business model. Borrowing is not inherently a sign of weakness: long-term financing may be appropriate for long-lived assets. The main concern is a mismatch between the maturity of financing and the assets or activities it supports, particularly when the company depends heavily on short-term funding that may not be renewed. Balance sheet analysis becomes more useful when it connects long-term financing with the cash tied up in day-to-day operations. Working capital (WC) represents the portion of stable financing available after funding non-current assets. Working capital requirement (WCR) measures the net funds tied up in the operating cycle, primarily inventory and receivables less operating payables. The difference between the two helps explain the company's net cash position. The figures depend on the industry. Manufacturers often finance substantial inventories and receivables, whereas some retailers receive customer payments before paying suppliers and may therefore operate with negative WCR. These are simplified analytical formulas. The treatment of leases, provisions, non-operating items and other financing instruments depends on the accounting framework and analytical method. WC may also be calculated as current assets minus current liabilities when classifications are consistent. Negative WC indicates that stable funding does not fully cover non-current assets. This can create refinancing pressure, but it does not automatically mean that a company is insolvent. Some business models generate a structurally negative WCR, which may offset part of that pressure. Analyse the complete cash conversion cycle before drawing a conclusion. If WC is below WCR, the company has a net short-term financing need. This may be covered by bank facilities or other funding sources. The key questions are whether the facilities are committed, how much headroom remains, and whether the company can withstand a downturn or delayed customer payments. A weak financial structure combined with a high WCR can increase the likelihood of late payments. A fall in sales, a significant unpaid receivable or a reduction in bank facilities may then put immediate pressure on liquidity. Nevertheless, balance sheet ratios cannot be interpreted in isolation. A trading company, a manufacturer and a capital-intensive industrial business have very different financing needs. Examine trends over several periods, debt maturities, available liquidity, profitability, and the company's actual payment behaviour. Read the balance sheet alongside the profit and loss statement. The objective is not simply to calculate ratios: it is to understand the business behind the figures and decide which credit terms and credit limits are appropriate. My DSO Manager helps credit management teams monitor customer risk, organise credit analysis, manage credit limits and coordinate collection actions. Connectors to financial information providers and configurable workflows support consistent credit decisions.How to Analyse a Balance Sheet and Assess Credit Risk
What is a balance sheet?
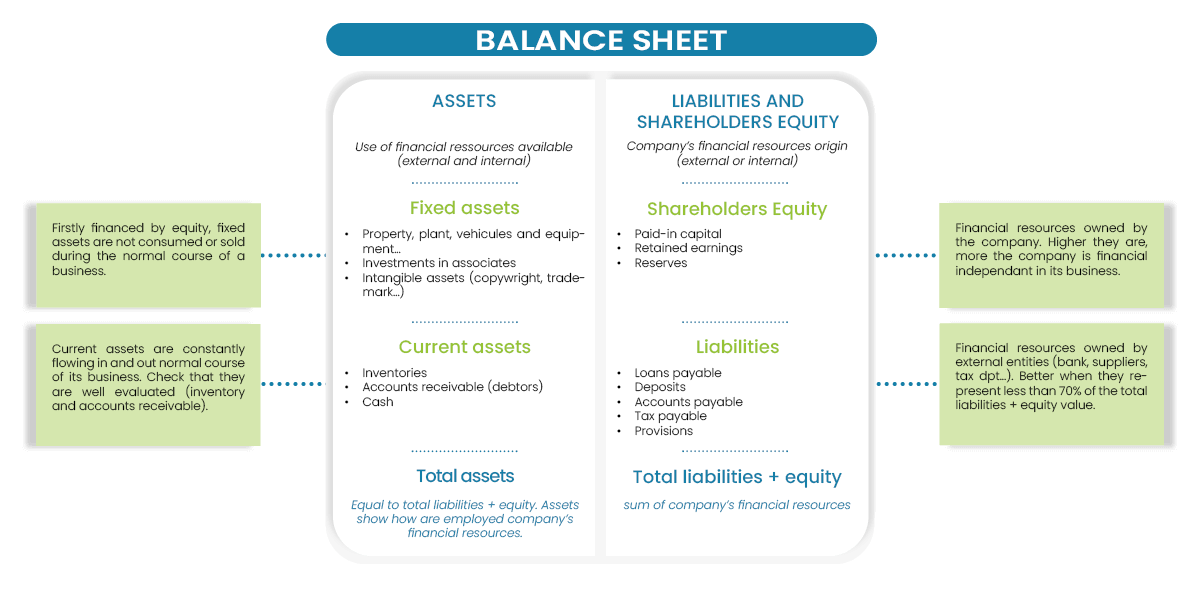
How to assess a company's financial structure
A dynamic view: working capital and working capital requirements
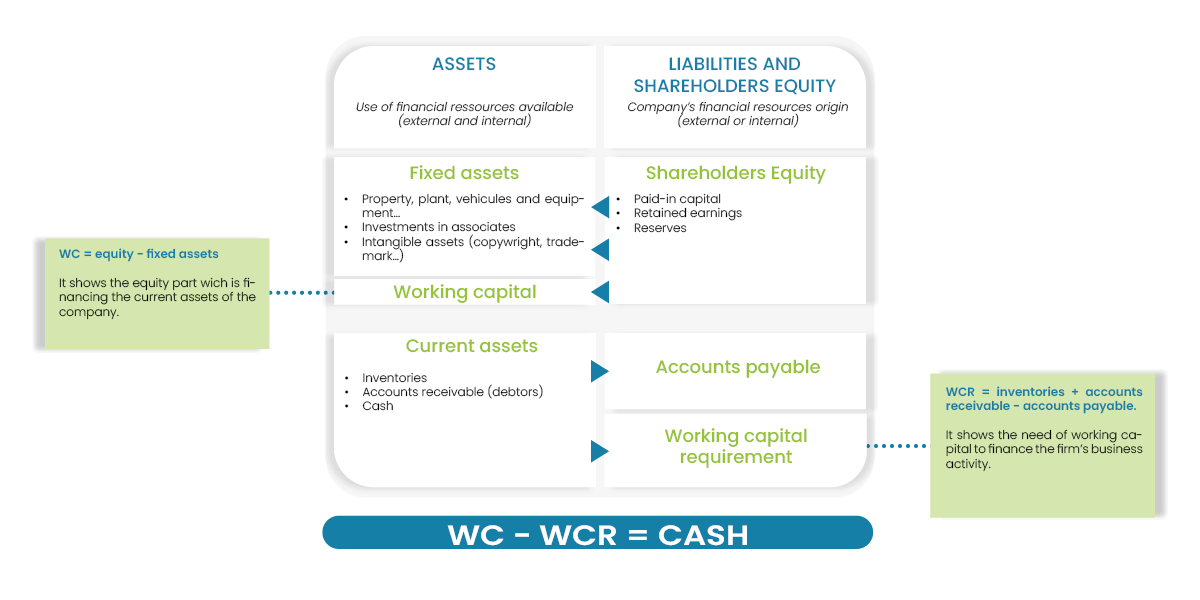
How to calculate WC, WCR and net cash
Indicator
Formula
What it tells you
Working capital (WC)
Equity + long-term financial liabilities - non-current assets
Stable funding remaining to support the operating cycle.
Working capital requirement (WCR)
Operating current assets - operating current liabilities
Net financing required by day-to-day operations.
Net cash position
WC - WCR
Net cash or net short-term financial debt, subject to consistent classification.
What does negative working capital mean?
What does negative net cash mean?
How to interpret a balance sheet for customer credit risk
Manage credit risk with My DSO Manager
Quick & simple One of the Best interpreattions!!
Well explained.... Nicely presented
Thank you.
Analyze the Profit and Loss account
How to Analyse a Profit and Loss Statement A practical guide to understanding a customer's revenue, profitability and financial resilience before making a credit decision. Financial statement...
Balance Sheet Ratios: Formulas, Examples & Credit Risk
Key Balance Sheet Ratios: How to Calculate and Interpret Them Balance sheet ratios help credit managers assess a customer's financial resilience, short-term liquidity and ability to meet payment...
The aging balance
The accounts receivable aging report (also called an aging balance or aged receivables report) is one of the most useful tools in credit management. It shows how much each customer owes, when...