Economic shocks can rapidly change a customer's ability to pay. During a crisis, credit managers must look beyond historical financial statements and reassess liquidity, payment behaviour and business resilience. Whether a crisis is financial, geopolitical, energy-related, sector-specific or caused by a major disruption within a company, the objective remains the same: anticipate payment difficulties, protect cash flow and make proportionate credit decisions without unnecessarily undermining viable customer relationships. Crises accelerate change. Demand can collapse, input costs can rise, supply chains can be disrupted, financing can become more expensive and customers can face unexpected operational difficulties. The impact varies considerably between industries and individual businesses: some are severely affected, while others adapt or benefit from new opportunities. Temporary measures such as loan extensions, payment deferrals, public support or emergency financing may help a company absorb the initial shock. However, they can also postpone the recognition of financial difficulties. A business may continue paying suppliers while accumulating liabilities or exhausting its liquidity reserves. Historical accounts and external credit ratings remain valuable, but they describe a situation that may already have changed. The immediate priority is to determine whether the customer can generate and preserve enough cash to meet its obligations over the coming weeks and months. See also The Credit Analysis for the broader framework of customer risk assessment. Two simplified scenarios help illustrate the relationship between economic recovery and customer credit risk. Activity falls sharply and then recovers relatively quickly. Companies with adequate liquidity, financing and operational flexibility may be able to absorb the temporary shock. Activity drops and remains depressed for an extended period. Fixed costs, debt repayments and weaker cash inflows can gradually erode liquidity, increasing the risk of late payments and insolvency. These shapes are illustrative rather than predictive. The actual outcome depends on the customer's sector, cost structure, access to finance, cash reserves and ability to adjust operations. A sharp decline in sales does not necessarily cause an immediate cash shortage. Companies may still collect invoices issued before the downturn, while cost reductions, additional financing or payment deferrals provide temporary relief. The problem can emerge later: cash receipts decline as the lower level of sales feeds through to accounts receivable, while wages, rent, suppliers, taxes and loan repayments continue or resume. This creates a time lag between the economic shock and its full impact on liquidity. It is therefore important to monitor both actual receipts and expected future cash flows. Payment patterns are especially valuable: see The Payment Profile for an explanation of how customer payment behaviour supports credit decisions. When conditions change rapidly, relying solely on annual accounts or an external credit rating can leave significant gaps. Financial information providers and credit insurers remain useful, but their assessments may reflect information collected before the disruption. Changes in credit insurance limits can signal concern, although they may also reflect an insurer's portfolio exposure or risk appetite rather than the specific customer's financial position. Credit managers should combine several complementary sources: Direct contact with customers can provide timely information, especially when combined with your own accounts receivable data and collection history. For a broader methodology, consult The Credit Analysis and Get Information About Your Clients. In a crisis, the first objective is often to estimate how long the business can continue meeting its payments under different recovery scenarios. A practical analysis does not necessarily require a complex model, but it must use credible assumptions and distinguish liquidity from accounting profit. Simplified cash forecast Build a weekly or monthly forecast over an appropriate horizon and identify the lowest projected cash balance. If available liquidity becomes negative, the business will need additional funding, lower outflows, faster collections or other corrective action. For example, a customer with substantial receivables may still face a short-term funding gap if those receivables are collected after its main payments fall due. Conversely, strong equity does not guarantee that cash will be available at the right time. Historical accounts remain relevant for assessing the starting position and financial resilience, especially when analysed alongside recent management figures and cash forecasts. Review Balance Sheet Analysis and Key Balance Sheet Ratios alongside the cash forecast. The purpose of credit analysis is to support decisions that protect the supplier without unnecessarily damaging viable customer relationships. Depending on the assessment, the company may: If temporary support is granted, define the duration, payment schedule, information requirements and consequences of non-compliance. Consider whether banks, shareholders or other suppliers are also contributing to a credible recovery plan. Avoid becoming the only party financing a structurally unsustainable situation. These decisions should reflect the company's own financial capacity and Credit Management Strategy. For further discussion of accountability, see Credit Risk: Who Decides?. Effective crisis management should not begin only when customers stop paying. It requires an early-warning process that combines financial information, payment behaviour, direct dialogue and forward-looking scenarios. The central lesson is that creditworthiness is dynamic. A strong balance sheet and a favourable historical rating do not eliminate the risk of a sudden liquidity shortage. Equally, a temporary difficulty does not automatically mean that a long-standing customer has become unviable. The role of the credit manager is to make timely, informed and proportionate decisions that protect the supplier's cash flow while supporting sustainable business relationships.Crisis Management in Credit Management: How to Assess and Control Customer Risk
Why crises challenge traditional credit risk models
V-shaped and L-shaped crises: why the recovery path matters
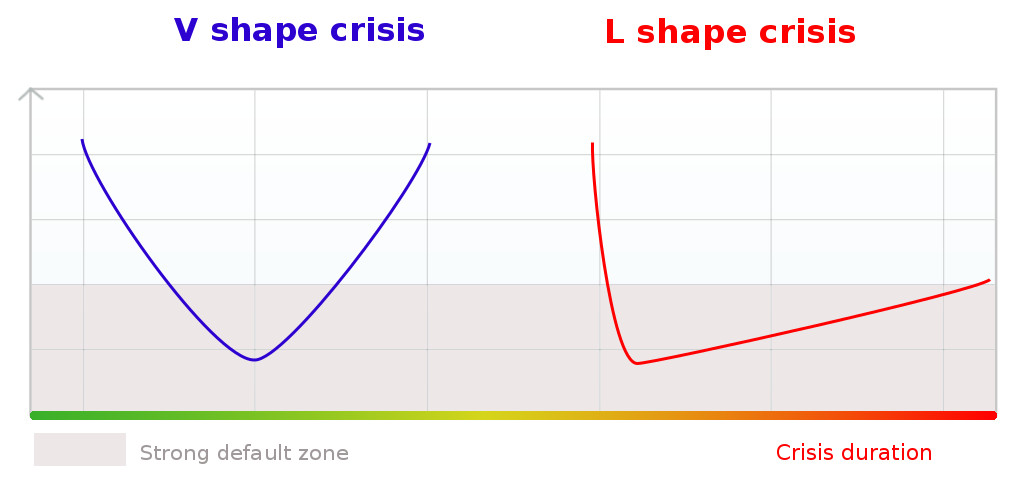
V-shaped recovery
L-shaped recovery
The long tail of defaults: why payment difficulties may appear later
How to reassess customer credit risk during a crisis
Information
What to investigate
Why it matters
Cash and available financing
Cash balances, undrawn facilities, funding availability and debt maturities
Immediate capacity to absorb a shortfall
Sales and order book
Recent revenue, order cancellations, backlog and recovery prospects
Likely future cash receipts
Customer payments
Overdue balances, broken promises, payment trends
Early evidence of financial pressure
Fixed costs and liabilities
Payroll, rent, debt service, deferred taxes and other obligations
Minimum cash outflows and future repayment pressure
Business resilience
Profitability, equity, sector exposure, ability to adapt
Capacity to withstand a prolonged disruption
How to evaluate a company's financial resilience
Six inputs for a simplified liquidity forecast
Closing cash = Opening cash + Cash inflows - Cash outflowsTurn the analysis into practical credit decisions
Building a resilient credit management approach
Practical priorities for credit managers
