Collection level 3 is the final stage of amicable B2B debt collection. Previous reminders and discussions have not produced payment. The Credit Manager must now bring the amicable process to a clear conclusion, normally through a formal notice demanding payment by a specified deadline.
The objective remains to obtain payment without litigation. But the supplier must also demonstrate that its contractual payment terms are meaningful and that continued non-payment will have consequences.
The last stage before litigation
By the time an account reaches level 3, the supplier has already attempted preventive collection, collection level 1 and collection level 2. The customer has had several opportunities to pay, explain a problem or agree on a solution.
An unpaid invoice affects the supplier's cash flow, profitability and financial position. It also creates an imbalance in the commercial relationship: the seller has fulfilled its obligations, while the buyer has not met the agreed payment commitment.
There is no reason to let an undisputed invoice remain unpaid indefinitely. When ordinary reminders have failed, the supplier must adopt a firmer position. However, before sending a formal notice, verify that previous messages reached the correct contacts. Repeated unanswered emails may reveal an incorrect address or an ineffective contact strategy rather than a deliberate refusal to pay.
A formal notice: a decisive step
The central action at collection level 3 is the formal notice of payment (often called a letter of demand or, in France, a mise en demeure). It should identify the outstanding invoices, state the amount due, set a final payment deadline and explain the actions the creditor may take if payment is not received.
Sending the notice shows that the amicable collection phase is coming to an end. It often produces the psychological effect needed to unlock payment: the debtor understands that the supplier is prepared to act.
Use a traceable delivery method that provides evidence of sending and, where appropriate, receipt. A registered letter with acknowledgement of receipt is a common solution. An electronic registered delivery service may also be appropriate where it meets the applicable legal requirements.
In some jurisdictions and procedures, a formal demand is legally required before specific remedies can be pursued; in others, it is not a universal prerequisite for filing a claim. The Credit Manager should therefore ensure that the notice and delivery method are suitable for the contract, jurisdiction and intended next step.
Do not send a formal notice as an empty threat. If the debtor ignores the deadline and nothing happens, future collection actions lose credibility.
Collection level 3 process
The following illustration shows a typical escalation sequence. It is an operational example rather than a mandatory timetable: the dates must be adapted to the customer, contractual terms and the company's credit policy.
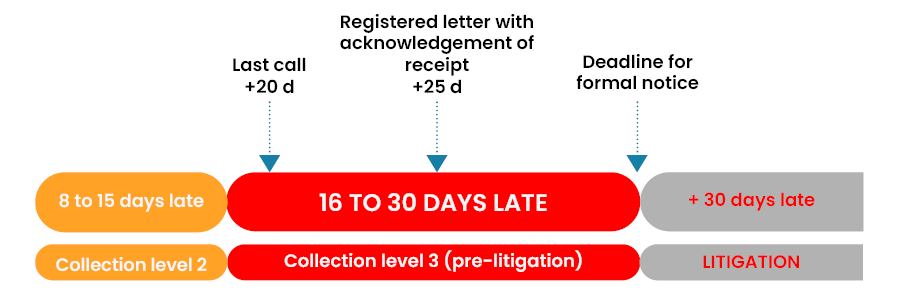
| Stage | Action | Objective |
|---|---|---|
| J+20 | Final call or interactive email | Confirm the reason for non-payment, request immediate settlement and explain the forthcoming formal notice |
| J+25 | Formal notice with proof of delivery | State the debt, provide a final deadline and make the next steps explicit |
| After the notice deadline | Escalation decision | Proceed with the agreed recovery action if the debt remains unpaid and no credible resolution has been reached |
The final telephone call can still be effective. It gives the customer one last opportunity to act before a formal document is issued. But it must not restart an endless sequence of reminders.
The whole company must speak with one voice
A formal notice should not be an isolated initiative taken by the collection department without informing the rest of the organisation. Sales, finance and management must understand the situation and support the decision.
A customer should not receive a firm demand from the Credit Manager while being reassured by a salesperson that payment can wait. This contradiction undermines the company's credibility and makes collection more difficult.
The escalation process, approval responsibilities and possible commercial measures should be defined in the company's credit policy. Where appropriate, the company may also review further deliveries or new credit exposure, consistently with its contractual obligations.
What if the customer genuinely cannot pay?
Some customers do not pay because they are experiencing financial difficulties, rather than because they are ignoring their obligations. A formal notice does not create cash that the debtor does not have.
Where the business case supports it, a negotiated and documented payment plan may offer a better prospect of recovery than immediate litigation. The plan should specify amounts, dates, responsibilities and the consequences of missed instalments. It should also be assessed against the customer's financial position and any credit insurance obligations.
Negotiation does not mean accepting vague promises. A realistic, written payment plan is preferable to a succession of commitments that are never honoured.
After the deadline: act on the decision
If the deadline expires without payment or an acceptable agreement, the company should take the next action provided for in its escalation policy. Depending on the case, this may include:
- Referring the file to an external collection agency or legal adviser.
- Starting an appropriate judicial recovery procedure.
- Notifying the credit insurer and following the policy's claim or overdue-debt reporting requirements.
- Reviewing credit limits, further deliveries and other exposures to the customer.
Before escalating, check that the supporting documents are complete: contract or purchase order, invoices, proof of delivery or performance, customer correspondence, account statement, dispute history and evidence of the formal notice.
Litigation is not the objective. It can be costly, time-consuming and uncertain. Nevertheless, the creditor must be prepared to follow through when the amicable phase has demonstrably failed. Otherwise, the debtor learns that the company's deadlines have no real meaning.
See also our tutorial on collecting unpaid receivables and the guide to applying collection scenarios.
Conclusion
Collection level 3 is the moment when the company demonstrates that it intends to enforce its payment terms. A clear formal notice, coordinated internal action and a credible next step can resolve many overdue accounts without legal proceedings.
The purpose of the final amicable stage is not to threaten the customer repeatedly. It is to obtain a decision: payment, a credible agreement or the start of further recovery action.


