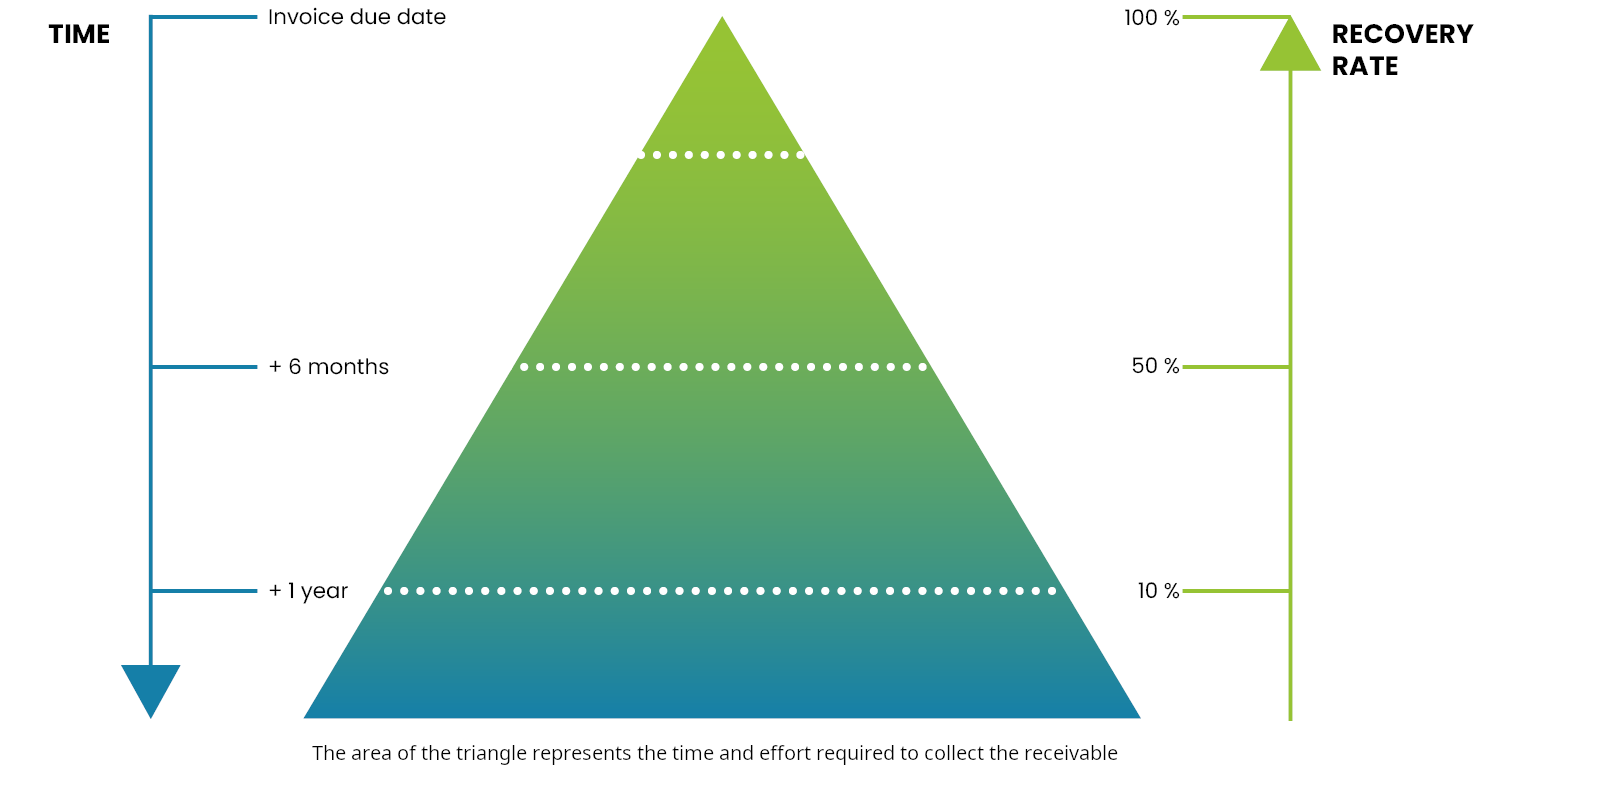
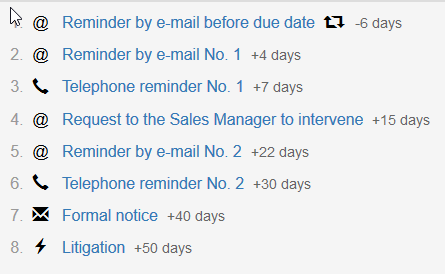
Cash collection is an art. It combines financial expertise, organisational discipline, interpersonal skills and a detailed understanding of how customers operate. The best collection professionals do far more than request payment: they identify and resolve the obstacles that prevent invoices from being paid on time. Positioned at the crossroads of finance and sales, the collector has an exceptional view of the weaknesses in the order-to-cash process. Invoice errors, unresolved disputes, missing documents, poorly allocated payments and internal communication failures all become visible through customer conversations. Effective collection therefore contributes not only to cash flow but also to the continuous improvement of the company. The reality of B2B collection is far removed from the popular image of aggressive debt recovery. Its purpose is to obtain payment while preserving a constructive, demanding and sustainable commercial relationship. The difficulty of cash collection lies in the need to combine skills that can appear contradictory: firmness and empathy, rigour and flexibility, automation and personal judgement. This explains why performance can vary so widely between collectors managing comparable portfolios. It also explains why reducing collection to a low-value administrative task is a mistake. The potential gains extend well beyond overdue receivables: they include better customer service, more reliable information and improvements throughout the quote-to-cash process. Time is a decisive factor in collection performance. As a receivable ages, obtaining payment often becomes more difficult. The customer may face deteriorating finances; supporting documents may be harder to locate; contacts may have changed; and resolving old accounting entries may require disproportionate effort. The older the unpaid invoice, the more time and energy are required to collect it, while the chances of recovery decrease. A commonly accepted collection statistic is that only 50% of receivables are recovered after six months of payment delay. This illustrates why acting quickly is essential. The original Triangle Express concept illustrates this relationship: as time passes, the effort required to recover an invoice increases while the prospect of recovery generally decreases. The objective is to remain at the top of the triangle by acting promptly and resolving problems before they become entrenched. To control time, every invoice should follow an appropriate collection scenario. The process begins, where appropriate, before the due date and progresses through increasingly firm actions, with a defined end to the amicable phase. The sequence is not intended to generate reminders indefinitely. Its purpose is to identify and resolve the cause of non-payment at each stage. Genuine disputes and other blocking issues require their own coordinated actions and deadlines. At the end of a properly managed amicable process, the remaining unpaid invoices should primarily be those involving significant financial difficulties, persistent refusal to pay or other unresolved exceptional circumstances. Whatever you do, you educate your customers. If you allow payment deadlines to pass without reacting, you teach customers that your invoices can be paid late. If you follow up precisely and consistently, you reinforce the importance of contractual due dates. Contrary to a common misconception, rigorous collection can strengthen a commercial relationship. Unresolved problems and accumulated unpaid invoices are much more likely to damage it. See Time and Collection Management. Sending generic reminders blindly to a shared mailbox is rarely the best way to obtain payment. In large companies and public-sector organisations, invoices pass through defined purchasing, approval and payment processes. The supplier must understand those processes and identify the contacts who can act. A delayed payment is usually the visible consequence of an underlying problem. The collector's task is to determine what is blocking the invoice, then address the relevant person or department: buyer, operational approver, accounts payable, treasury or another decision-maker. The right action must be carried out at the right time, by or with the right person, using the right information. For example, an accounts payable clerk may confirm that an invoice is blocked because the purchase order number is missing. Repeated reminders to that clerk will not solve the issue. The effective action is to obtain the correct information from the purchasing or operational team, provide it to accounts payable and verify that the invoice has been released for payment. All relevant customer information should be accessible in one place: contacts, approval rules, invoice requirements, previous actions, explanations, commitments and unresolved disputes. Each new interaction must build on the previous one rather than start the investigation again. How can a supplier agree with a customer on what should be paid if its own accounts receivable records are inaccurate? The customer account must be kept clear and up to date. Payments should be allocated promptly, credit notes matched correctly and differences between the supplier's accounts receivable ledger and the customer's accounts payable ledger investigated without delay. An invoice that has already been paid but remains open because of an allocation error can generate pointless reminders and seriously damage the supplier's credibility. The reverse situation is equally problematic: an unidentified payment may conceal a genuinely overdue invoice. The Triangle Express applies here too. The older an unexplained accounting entry becomes, the harder it may be to reconstruct the transactions, identify the right contacts and reconcile the accounts. Cash collection is, fundamentally, a communication process between two organisations whose information systems, accounting rules and operating procedures are not naturally aligned. These differences are already difficult enough without adding poor internal accounting practices. The collector is a partner to the customer's accounts payable team. By supplying accurate statements, supporting documents and reliable information, the collector makes it easier for the customer to process invoices and pay on time. This requires close coordination between accounting, collection, sales administration and customer service. Keeping the ledger accurate is not merely an accounting concern: it is a prerequisite for efficient collection. The quality of the relationship with customer contacts is essential. A collector must establish trust and maintain constructive exchanges while remaining firm about the obligation to pay invoices on their contractual due dates. This requires sensitivity to understand the customer's situation and identify obstacles, combined with the rigour needed to obtain concrete commitments. In other words, an iron fist in a velvet glove. Good relationships are not limited to the customer. Collectors must also know how to mobilise colleagues in sales, accounting, customer care and operations. Their involvement serves three objectives: The collector acts as a bridge between finance and sales: two functions with different priorities, but a shared interest in maintaining profitable customer relationships. The quality of the relationship is the drop of oil that allows the gears to turn, even when the mechanism has imperfections. Professional, solution-oriented exchanges make it easier to resolve the inevitable problems that arise between two businesses. Every communication, whether with a customer or an internal colleague, should aim to obtain a useful action. The purpose is not simply to send another email or log another call: it is to move the invoice towards resolution and payment. The four pillars reinforce one another. Prompt action is ineffective if it reaches the wrong person. Excellent relationships cannot compensate for inaccurate accounts. And a perfectly reconciled ledger will not generate cash if no one takes responsibility for the next action. Modern credit management software can support these principles by centralising information, organising action agendas, automating appropriate reminders and coordinating dispute resolution. Such tools become especially valuable when teams manage large portfolios of customers and receivables. But software does not replace professional judgement. Its role is to amplify the collector's effectiveness, not to reduce collection to a succession of automated messages. Combining these four pillars is difficult because they require complementary, sometimes contradictory qualities. That is why cash collection is a genuine professional art. The best collectors obtain payment while solving operational problems, improving the company's processes and protecting the customer relationship. Their contribution goes far beyond reducing overdue balances: it strengthens cash flow, profitability and the quality of the entire order-to-cash process. Recognising this expertise, and giving collection teams the information, autonomy and tools they need, is one of the most effective ways to improve financial performance.The four pillars of effective cash collection
1. Time management: act before it is too late
The “Triangle Express” principle
Apply a progressive collection scenario
2. Adapt to the customer's organisation
3. Ensure the daily quality of accounts receivable management
4. Build excellent relationships while remaining demanding
Combining the four pillars: the collector's real expertise
Pillar
Key question
Expected result
Time management
Are we acting at the right moment?
Fewer invoices become seriously overdue.
Customer organisation
Are we speaking to the person who can resolve the issue?
Obstacles are identified and removed faster.
AR management quality
Are our customer accounts accurate and understandable?
Fewer disputes, reconciliations and unnecessary reminders.
Relationships
Are our exchanges leading to useful action?
Stronger cooperation and reliable payment commitments.
Conclusion: cash collection is a profession, not a repetitive task
Category's rubrics
Invoicing rulesHow to efficiently manage your disputes?The aging balanceLate delivery penaltiesHow to apply collection scenarios?How to collect prior due date?What is the collection level 1?What is collection level 2?What is the collection level 3?Setting up SEPA direct debit: a step-by-step guideNegotiate a payment planTime and collection managementThe keys of cash collectionLate payment penaltiesFixed recovery compensationTrade receivable collection mediaElectronic Registered DeliveryGet paid from Public Sector CustomersLegislation on Amicable Cash CollectionHow to choose the best credit management software?Improve your processes with cash collectionSME organizations for cash collectionHow to do green cash collection?Artificial Intelligence in Cash Collection | Complete GuideElectronic Invoicing and Cash Collection: Complete Guide
Comments
Comment this page
Comments are subject of editor's review before publication
Last comments
R.H.
09-01-2026
A must read for any newcomer to Credit and collections and a valuable reminder to teams currently working in the domain. We have an excellent tool in My DSO manager, to be fully leveraged to accelerate our Cash Collection.
Articles on the same topic
Category
My DSO Manager presentation, collection and credit management software
11-12-2026
My DSO Manager is a SaaS platform dedicated to credit management, cash collection and customer risk management. Designed by credit management professionals, it brings together the...
Rubric
What is the collection level 1?
11-09-2026
The first collection level begins when an invoice has reached its due date and remains unpaid. Its purpose is simple: understand the reason for the delay, obtain immediate payment whenever...
Rubric
What is collection level 2?
11-09-2026
Collection level 2 is the stage at which an unpaid invoice can no longer be treated as a simple oversight. After preventive collection and the first reminders, the supplier must establish...