Amicable B2B cash collection is, above all, a matter of communication. Its effectiveness depends on the ability to deliver the right information to the right person at the right time, and to obtain the action needed to release payment.
Which channel should you use: e-mail, telephone, post, SMS, a customer portal or an electronic registered letter? There is no universal answer. The most effective approach combines different channels according to the customer, the reason for non-payment and the stage of the collection process.
Collection effectiveness depends on much more than the channel
Before choosing a communication medium, several characteristics of the company and its customers must be considered:
- Organisation: Who manages accounts receivable collection? Is it part of finance, sales or a dedicated credit management department?
- Business culture: Who owns the customer relationship? Can collectors contact the buyer or accounts payable team directly, or must every contact go through sales?
- Processes: How well are collection, dispute resolution and credit risk management coordinated? Are credit limits and account blocking rules aligned with the collection process?
- Information systems: Does the team work with an ERP, spreadsheets and an e-mail client, or with dedicated credit management software?
- Customer profile: Small businesses, large organisations, public bodies, domestic customers and international customers do not have the same approval and payment processes.
Once these factors are understood, an essential question remains: which communication channels will help customers resolve their payment issues most efficiently?
The aim is not to multiply reminders. It is to make each interaction useful. A reminder that does not reach the person able to act, or does not contain the information required to resolve the issue, is unlikely to produce payment.
Traditional collection channels
Postal letters
Postal mail is a traditional symbol of debt collection. Today, it is generally most relevant in the advanced stages, when exchanges must be formalised or when a particular legal procedure requires a specific form of notification.
Its drawbacks are substantial: printing and handling, delivery time, postage costs, limited interactivity and the environmental impact of paper and transport. A letter may also fail to reach the person who can authorise payment.
Best use: formal notices, pre-litigation steps and situations where a physical document is required or strategically useful. Check local rules before assuming a particular mailing method has legal effect.
Telephone calls
The telephone is valuable for understanding a customer's position, clarifying a disagreement, negotiating a solution and obtaining a credible payment commitment. It enables a genuine personal relationship and helps the collector interpret the explanations given.
But the telephone has important limitations. Calls take time, depend on the other person's availability and are poorly suited to communicating long account statements, numerous invoices or supporting documents.
The telephone is primarily a tool for resolving problems, not for mass collection. Using highly qualified collectors to make routine calls on hundreds of invoices is often inefficient. Their expertise is much more valuable when dealing with complex disputes, negotiation or unusual financial difficulties.
After an important call, record the agreed actions, responsible persons and deadlines, and confirm them in writing when appropriate.
Fax
Fax is largely obsolete, but it may remain useful for a limited number of customers who still rely on it. Its effectiveness depends on the recipient actually using the channel and on the message reaching the correct department or contact. A generic company fax number offers little assurance of that.
Fax should be treated as an exception, not a standard B2B collection channel.
E-mail is one of the most versatile channels for B2B collection. It can be addressed to named contacts, sent promptly and enriched with invoices, account statements, supporting documents, secure document links and payment links.
It also makes it easy to involve several relevant people, document the history of an issue and obtain a written response. When personalised and supported by accurate information, e-mail is particularly well suited to routine reminders and coordination.
However, e-mail is often a poor medium for resolving conflict. Misunderstandings can intensify in long exchanges, especially when a dispute is emotional or commercially sensitive. In those situations, a direct telephone conversation is usually more productive.
High volumes of automated e-mails are not, by themselves, a sign of effective collection. The key measure is whether the communication leads to payment or removes a specific obstacle.
Customer visits and meetings
A face-to-face meeting, or an appropriately structured video meeting, can be extremely effective for strategic customers and complex situations. It helps align the supplier's accounts receivable processes with the customer's accounts payable organisation, identify recurring causes of delay and agree on a lasting operating model.
Such meetings can also improve the supplier's understanding of the customer's financial and operational situation. They require time, however, and should be reserved for relationships where the potential benefits justify the effort.
Digital and interactive collection channels
SMS and messaging
SMS is generally less suitable for complex B2B relationships, but can be effective for some small businesses and self-employed professionals. Consider a tradesperson working on site throughout the day: a short, well-timed message may be more convenient than an unexpected telephone call.
SMS can also help coordinate internal actions, for example by prompting a sales representative to respond to an urgent request. It is not suited to detailed account reconciliation, sensitive disputes or lengthy invoice lists.
Business messaging applications can play a similar role when the customer has agreed to use them. Ensure that communications are appropriate, secure and properly recorded in the customer history.
Interactive e-mails and customer portals
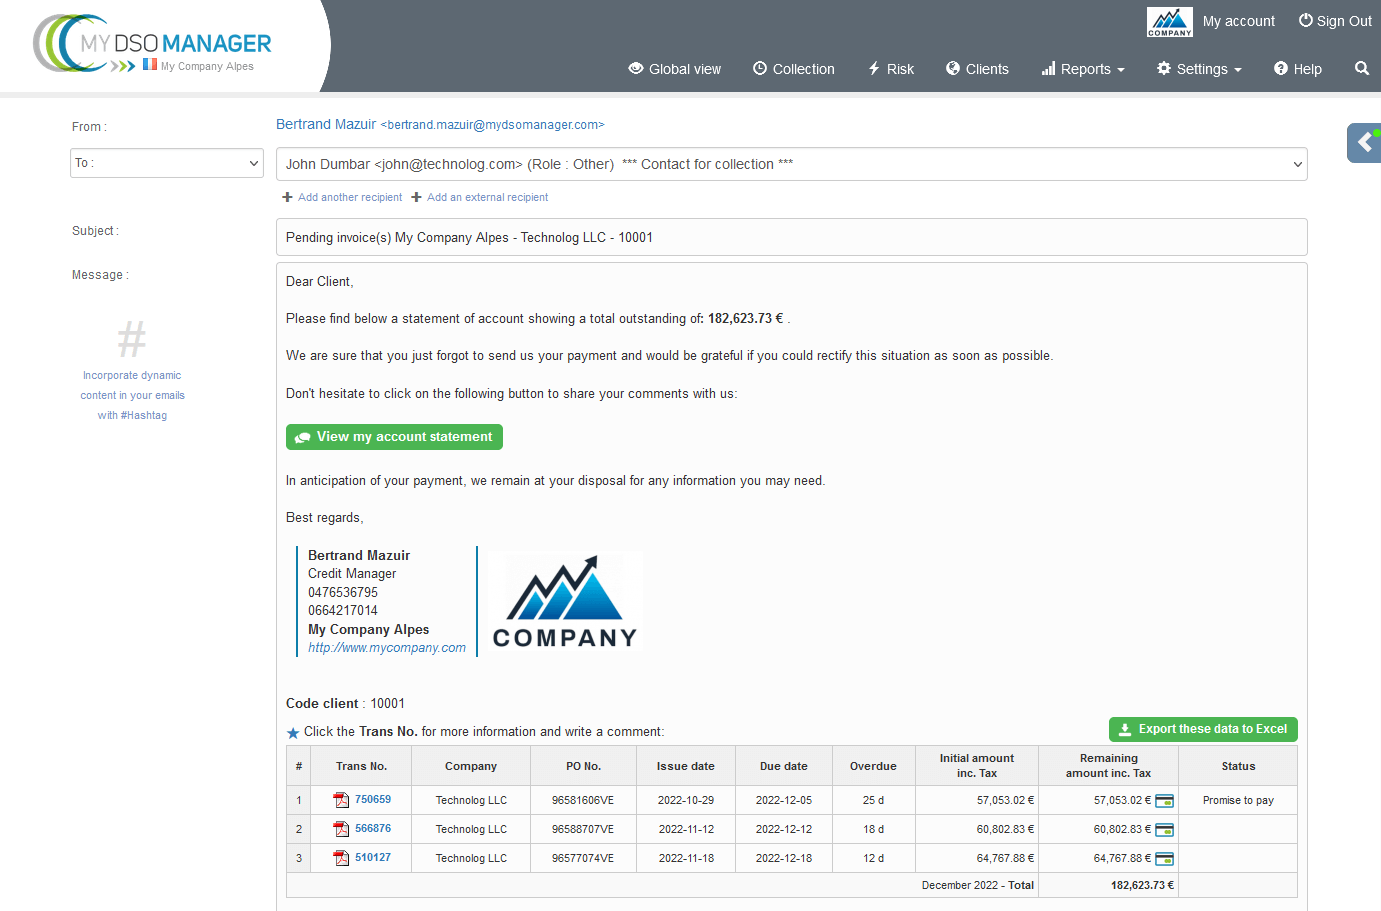
Interactive e-mail extends a conventional message by allowing the recipient to access relevant account information and respond through a dedicated online interface. Rather than sending an isolated reminder, the supplier gives the customer a practical way to inspect invoices, share comments, identify disputes or communicate payment commitments.
In My DSO Manager, interactive e-mails can support exchanges with customers and internal stakeholders, including sales and customer service teams. The objective is to turn the reminder into a structured, traceable interaction that moves the issue towards resolution.
Customer accounts payable portals are another important channel. Some large buyers require suppliers to upload invoices, follow approval statuses or submit disputes through a portal. In such cases, sending more reminders may be less useful than checking and correcting the information in that system.
A well-designed interactive interface can allow a customer to download invoices and statements, export account data, explain deductions, report disputes, make a payment or provide a payment date. The recipient should have access to current information without having to request another document from the collector.
For internal colleagues, the same principle makes it easier to request assistance from sales or customer service and track their responses. The aim is a shared, actionable record rather than fragmented e-mail threads.
Electronic registered letters
Electronic registered delivery can be a faster and less paper-intensive alternative to traditional registered mail. In the European Union, qualified electronic registered delivery services benefit from a specific legal framework under the eIDAS Regulation. However, the conditions for equivalence with a paper registered letter depend on the applicable law and the type of notice.
For formal demands and pre-litigation communications, use a service that meets the legal requirements of the relevant jurisdiction. Electronic delivery should not be assumed to have the same evidential or procedural status everywhere.
Which channel should you choose?
| Channel | Best suited to | Main limitation |
|---|---|---|
| Routine reminders, account statements, document sharing and written coordination | Can aggravate misunderstandings or conflict | |
| Telephone | Negotiation, complex disputes, clarification and payment commitments | Time-intensive and unsuitable for large invoice lists |
| Interactive e-mail / portal | Shared information, customer responses, disputes and collaborative resolution | Requires appropriate tools and user adoption |
| SMS / messaging | Short reminders for selected small businesses or internal coordination | Limited detail and traceability if unmanaged |
| Postal / registered letter | Formal notices and advanced collection stages | Slower, costlier and less interactive |
| Electronic registered delivery | Formal electronic notices where legally appropriate | Legal requirements vary by jurisdiction |
| Customer meeting | Strategic accounts and recurring process failures | Resource-intensive |
| Direct system integration / e-invoicing | Invoice submission, status visibility, exception detection and structured data exchange | Depends on data quality, platform coverage and integration capabilities |
The right mix also depends on the number and value of invoices. A customer account containing hundreds of low-value invoices calls for a different approach from an account with two high-value invoices and a major unresolved dispute.
International customers, public-sector buyers, purchasing portals and complex approval processes may require additional adaptations. There is no ready-made formula: effective collection scenarios must be designed pragmatically around the realities of the business.
The future of collection: direct system interconnection
Digital transformation is changing the very nature of B2B communication. Increasingly, information can move directly between the seller's and the buyer's systems through APIs, structured electronic invoicing, supplier portals and other integrations.
Traditional reminders often compensate for a lack of visibility between those systems: the supplier does not know whether an invoice has been received, approved, disputed or scheduled for payment. Better interconnection can remove much of that uncertainty.
As systems become more connected, many routine reminders should become unnecessary. Electronic invoicing is an important accelerator of this change, although it does not eliminate genuine commercial disputes or payment risk.
The collector's role therefore evolves towards identifying exceptions, coordinating their resolution and managing situations that require human expertise. Telephone calls remain useful, but principally for negotiation and complex problem-solving rather than repetitive mass follow-up.
Electronic invoicing is an accelerator, not the end of credit management
Electronic invoicing can improve the reliability of invoice delivery, standardise information and, depending on the national framework and the platforms involved, make invoice statuses available sooner. It does not, by itself, guarantee that an invoice has been approved or will be paid. Its real value for credit management increases when invoice data and status information flow back into the seller's systems.
For example, a rejected invoice should trigger a correction workflow, not a routine payment reminder. An approved invoice that is overdue requires a different response. An invoice awaiting operational approval should be directed to the person able to release it. Knowing the reason for non-payment is more valuable than sending another message.
Public-sector platforms such as Chorus Pro in France illustrate this evolution. They can provide structured invoice submission and status information; when connected to credit management software, this information can help teams prioritise actions and address exceptions. The scope and detail of statuses vary by platform and integration.
From reminder media to interoperable processes
The next step is not simply to add more communication channels. It is to connect the systems of suppliers, buyers, banks and invoicing platforms through APIs and other secure exchanges. This reduces unnecessary manual follow-up and improves the quality of information available to everyone involved.
There will still be situations requiring human judgement: commercial disputes, complex deductions, financial difficulties and negotiations. These are precisely the cases where experienced credit managers add the most value.
Collection channels in My DSO Manager
Dedicated credit management software helps teams combine communication channels within coherent collection scenarios, schedule the right action at the right time and preserve a shared history of exchanges.
My DSO Manager supports e-mail, interactive e-mail, SMS, letters, telephone actions and other communication workflows. The value lies not only in sending messages but also in their quality, relevance, personalisation and timing.
The quality and speed of a communication matter as much as the channel
Two companies can both send e-mails and obtain very different results. One sends a generic message with an invoice number and an overdue amount. The other sends a personalised message containing an accurate statement, invoice copies or links, payment details, a clear explanation of what is expected and a direct way to respond.
The second approach saves time for the customer and the collector. It also reflects the quality of the supplier's internal processes and tools. A medium is only a vehicle: the information it carries, and the ease of acting on it, determine much of its effectiveness.
Speed matters too. When a dispute is raised, the relevant team must be informed quickly and a follow-up action scheduled. An interactive message that captures the issue but does not lead to its resolution has little value.
My DSO Manager and connected platforms
Beyond multichannel reminders, My DSO Manager can exchange information with external systems and platforms, including Chorus Pro in France. The objective is to combine collection actions with the operational information needed to solve problems, rather than relying exclusively on manual reminders.
Automation can help prepare or send appropriate communications, while qualified credit management professionals focus on the exceptions, decisions and negotiations where their expertise makes the difference.
Conclusion: communication is a means, not the objective
There are no inherently good or bad collection channels. Each is effective in certain circumstances and ineffective in others. A well-designed process combines e-mail or interactive e-mail for structured information exchange, telephone calls for complex issues and formal notices when escalation becomes necessary.
The purpose of collection is not to send reminders. It is to resolve the reasons for non-payment and obtain payment while preserving a constructive commercial relationship.
The best results come from accurate information, the right interlocutor, an appropriate channel and a clear next action. That is what turns communication into effective credit management.