In a small or medium-sized enterprise, who should be responsible for collecting customer payments: the sales team or the accounting department? The question sounds simple, but it reveals a fundamental characteristic of cash collection and credit management: they sit at the crossroads of commercial relationships and financial discipline.
In many SMEs, sales and accounting operate as separate worlds. Yet the payment of an invoice depends on both. The challenge is not simply to choose who sends reminders, but to establish an organisation in which responsibilities are clear and information flows between the people involved.
Commercial expertise
Customer knowledge, negotiation skills and the ability to resolve relationship issues.
Financial expertise
Accurate receivables data, payment allocation, overdue balances and follow-up discipline.
Shared objectives
Getting invoices paid on time while protecting profitable customer relationships.
Option 1: Sales managers lead cash collection
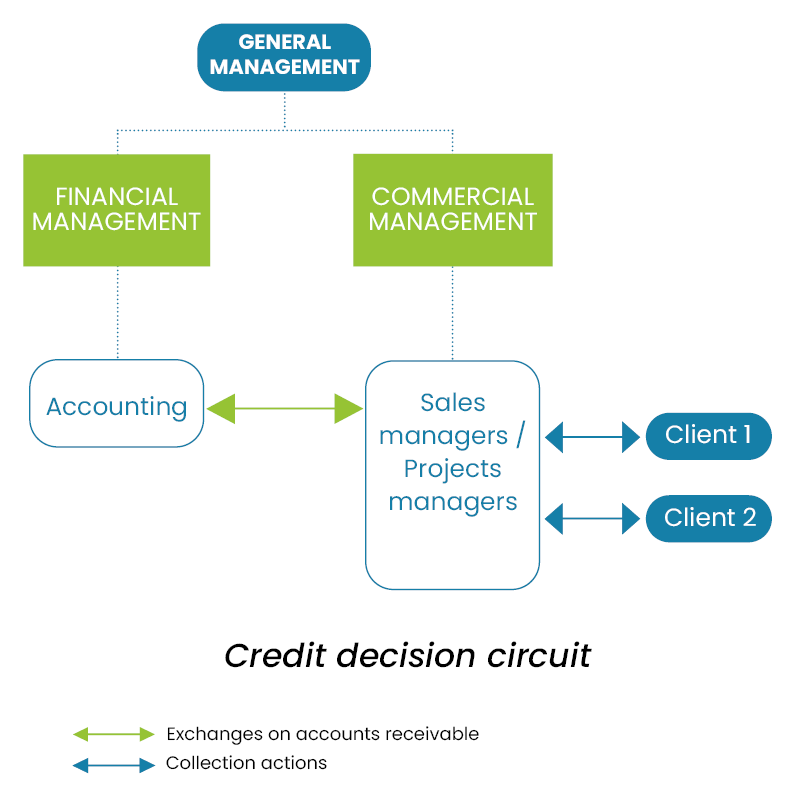
Some SMEs put salespeople or project managers on the front line of customer payment reminders. They may even introduce incentive schemes to encourage their involvement in an activity that is not necessarily part of their natural role.
For this model to work, a salesperson must become a little more like an accountant: understand the outstanding balance, distinguish a disputed invoice from a straightforward overdue payment and follow a disciplined collection schedule. Close, almost daily communication with accounting is essential.
The advantages
- Salespeople know the customer, their organisation and their current projects.
- They can quickly identify commercial issues behind a payment delay.
- The customer receives a message from an established contact.
The limitations
- Collection competes with prospecting, negotiations and new orders.
- Payment reminders may be postponed to avoid uncomfortable conversations.
- Collection requires specific accounting, organisational and interpersonal skills.
In practice, this organisation is rarely the most effective, although exceptions exist. A salesperson negotiating a new order may struggle to insist on payment of an overdue invoice at the same time. The immediate commercial opportunity often takes priority, and the collection action is postponed until a supposedly better moment.
But overdue receivables do not wait for a convenient commercial moment. Cash collection follows its own priorities and timetable. This is why making salespeople solely responsible can weaken performance, even when they are highly competent in their primary role.
Option 2: Accounting leads cash collection
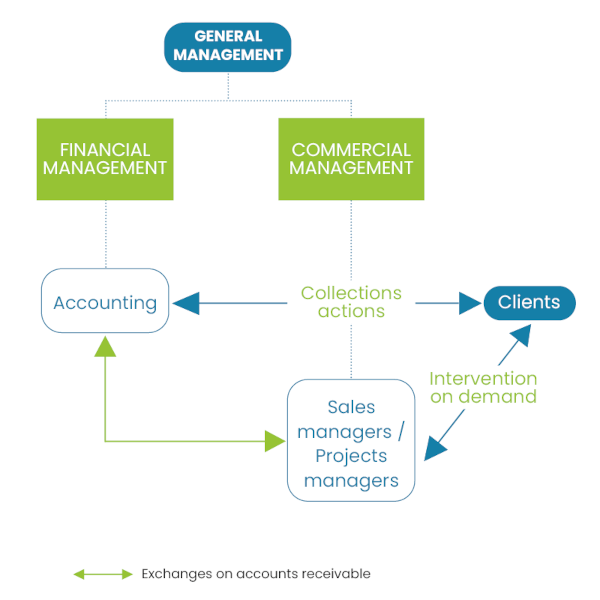
Other SMEs assign collection responsibility to accounting or finance. This organisation has an immediate advantage: the team already has detailed knowledge of the customer ledger, outstanding invoices, payment allocations and overdue balances. It can also communicate effectively with the customer's accounts payable department.
However, accounting must then become a little more commercial. A payment delay may involve a missing delivery document, a dispute over the service provided, a special customer arrangement or a delicate negotiation. These situations cannot always be resolved through a purely accounting approach.
The advantages
- Regular, structured monitoring of due and overdue invoices.
- Reliable financial information and direct dialogue with accounts payable.
- Salespeople remain available for commercial activities while being involved when useful.
The conditions for success
- Accounting must understand the customer's commercial context.
- Sales must be informed of important exchanges and payment problems.
- Disputes need named owners and deadlines, rather than being passed between departments.
Salespeople may initially resist this model because they want to retain control of the customer relationship. In many cases, however, they come to appreciate it: the organisation removes a task they do not particularly enjoy while keeping them informed and allowing them to intervene where their knowledge makes the difference.
The strongest benefit is the teamwork it creates between finance and sales. Each department contributes its own expertise, and the customer receives a consistent message.
Which organisation should an SME choose?
Both models can work. The right balance depends on the company's activity, customer portfolio, internal resources, commercial culture and objectives. There is no universal organisational chart.
What matters is recognising the hybrid nature of accounts receivable management and assigning responsibilities deliberately. In many SMEs, a practical model is to give accounting or a dedicated credit management function responsibility for the collection process, while involving sales and operational teams when a specific issue requires their intervention.
| Activity | Typical lead | Who should contribute? |
|---|---|---|
| Monitoring due dates and overdue balances | Accounting / credit management | Sales receives relevant visibility |
| Routine reminders and payment commitments | Accounting / credit management | Sales where customer context matters |
| Commercial or service disputes | Responsible operational team | Accounting tracks the financial impact and resolution |
| Negotiating exceptional payment arrangements | Finance / authorised management | Sales advises on the relationship |
| Credit limits and risk decisions | Finance / credit management | Sales contributes commercial intelligence |
| Escalation of serious overdue accounts | Defined decision-maker | Finance, sales and management coordinate |
This is an illustrative allocation of responsibilities, not a rigid rule. A very small business may combine several roles in one person.
Four foundations of an effective SME collection organisation
1. Anticipate customer risk
Use appropriate financial information, credit limits, credit insurance or other protections when justified by the exposure. Collection begins with good credit decisions, not with the first overdue reminder.
2. Set clear contractual conditions
Define payment terms, invoicing requirements, dispute procedures and applicable late payment provisions. Unclear conditions make every later conversation more difficult.
3. Share information and actions
Use a common view of invoices, customer exchanges, promises to pay and disputes. A collection or credit management solution can help coordinate accounting, sales, customer service and customers.
4. Define escalation paths
Decide who can approve a payment plan, suspend deliveries, refer an account to external collection or initiate legal action when the amicable process has failed.
Technology should support collaboration, not replace it
Cash collection software can help SMEs apply appropriate collection scenarios, organise follow-up actions, personalise reminders and share information across teams. But the software will not resolve an unclear division of responsibilities on its own.
Cash collection with My DSO Manager
My DSO Manager supports collection scenarios adapted to customer profiles, action planning in a dedicated calendar and configurable communication templates, including emails and interactive messages. It also enables different contributors, such as sales representatives, to access relevant customer information and coordinate actions around overdue invoices and disputes.
Conclusion: clear responsibilities, shared information and complementary skills
There is no reason to oppose accounting and sales. Their strengths are different, and effective cash collection depends on combining them intelligently.
An SME should choose the organisation that fits its size and business model, make one function accountable for the collection process, involve the right people at the right moment and equip them with reliable information. The result is not only better payment performance: it is also better customer service, fewer internal tensions and more consistent decisions.